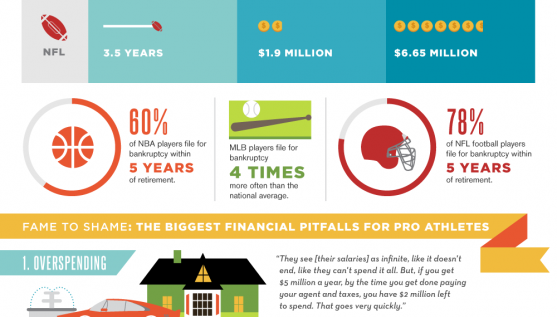
Let’s be real: there’s a certain magic in watching an NBA star float through the air for a dunk or sink a game-winner. We assume that massive contract—worth tens of millions—buys a lifetime of yacht trips and zero worries. But the hard truth, backed by a famous Sports Illustrated report from 2009, is that a staggering 60% of NBA players go broke within five years of retiring.
Yes, you read that right: six out of ten. It’s not just a sad sidebar; it’s a cultural cautionary tale that feels almost as legendary as the players themselves. And while the number has slightly improved in recent years thanks to better financial education, the core problem remains: easy money doesn’t teach hard discipline.
The Numbers That Will Make You Blink Twice
Let’s dig into the math, because it’s wilder than a fourth-quarter comeback. The average NBA career lasts just 4.5 years, but the average salary hovers around $8 million per season. That’s generational wealth—if you manage it like a librarian manages a quiet room.
Must Read
Instead, studies from the National Bureau of Economic Research show that 20% of NBA players file for bankruptcy within two years of retirement. That’s not just bad luck; it’s a system of lifestyle inflation, bad investments, and the pressure to “keep up with the LeBrons.”
Think of it this way: if you earn $100,000 a year and spend $110,000, you’re broke in a decade. Now imagine earning $10 million and spending $12 million on Bentleys, entourages, and court-side seats for your cousins. The math doesn’t change; only the zeros do.
The Classic Pitfalls: From Bentleys to Bad Business
What exactly drains a seven-figure bank account? It’s not just the “diamond-studded” grill or the six luxury cars. A huge chunk goes to entourage inflation—suddenly, you have 20 “best friends” who need salaries, flights, and hotel suites.
Then there’s the investment horror show. We’ve all heard about Antoine Walker, who earned $108 million and was broke by 2010, thanks to failed restaurant chains and gambling. Or Latrell Sprewell, who turned down a $21 million contract because he “had a family to feed.” Ouch.
Add in divorce, child support, and a lack of basic financial literacy, and you’ve got a recipe for a cautionary Netflix doc. The NBA even runs a mandatory rookie transition program, but as one agent told ESPN, “You can’t teach impulse control in a two-day workshop.”
Why This Happens (And Why It’s Almost Predictable)
Here’s the uncomfortable truth: the same aggression that makes a great player often makes a terrible money manager. You don’t become an NBA star by being cautious or saying “no.” You say yes to every shot, every workout, every risk.
 Every NBA Player Who Went Broke After Career End - YouTube
But money doesn’t work like basketball. It rewards patience, not passion. A 22-year-old with $5 million suddenly gets calls from “investment gurus” who promise 20% returns. Spoiler: those are often just legal hustlers with a nicer suit.
Add in culture—the expectation to support everyone from your high school coach to your fourth cousin—and you see how fast the well runs dry. “I’m not just spending on myself,” one retired player confessed. “I’m spending on my entire zip code.”
Fun (And Scary) Facts to Ponder
Did you know that Shaquille O’Neal once spent $1 million in one day on a car and jewelry? He later admitted he was “a dummy with money” before becoming a savvy investor. Or that Allen Iverson, who earned over $150 million, once had a rumor swirl that he couldn’t afford a burger? (He’s fine now, but the legend lives.)
Even the superstars slip: Michael Jordan lost millions in a failed baseball career and gambling rumors, but he had the Nike empire to fall back on. The average player doesn’t have a Jumpman logo. They have a pension of about $1,000 a month after retirement—hardly enough for a studio apartment in Beverly Hills.
Practical Tips for the Rest of Us (No, You’re Not an NBA Player)
Here’s where it gets personal. You don’t need a max contract to learn from these cautionary tales. The same principles apply to your $50,000 salary. First: live below your means, even when you get a raise. That bonus? Put 50% in savings before you touch the rest.
Second: ignore the entourage effect. You don’t have 20 cousins asking for money? Great. But your friends might pressure you into expensive dinners or vacations you can’t afford. Say “I’m on a budget” like it’s a badge of honor.
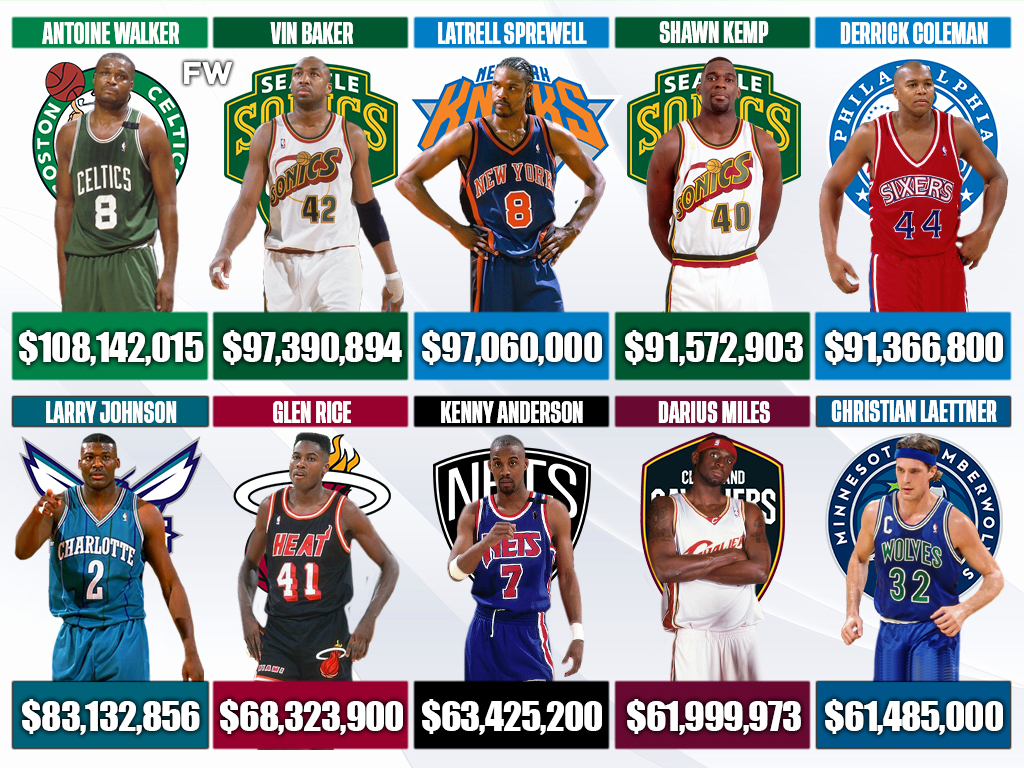 20 NBA Players Who Went Broke And Lost Millions Of Dollars - Fadeaway World
Third: invest in what you understand. NBA players lost millions on tech start-ups they couldn’t explain. You? Stick to index funds or a solid 401(k). Slow and steady doesn’t sell tickets, but it buys peace of mind.
And finally: build a post-career identity. Many athletes cling to the game because it’s all they know. You can avoid that by developing a hobby, skill, or side hustle outside your 9-to-5. When the “game” ends (or you get laid off), you’ll have something real to pivot to.
A Cultural Reality Check
This isn’t just a sports story. It’s a mirror for the “get rich or die tryin’” mindset that permeates modern culture. We glorify the flashy lifestyle—the Lamborghini, the champagne, the private jet—but we rarely show the quiet, boring work of wealth preservation.
Think about it: you see influencers renting yachts for a single photo. You don’t see them eating ramen in a studio apartment to afford the rent. The NBA players who stay rich are the ones who still clip coupons (or at least use a financial advisor). Guys like Tim Duncan and Steve Nash are famously frugal—and quietly millionaires for life.
Reflection: The Ball Don’t Lie, and Neither Does a Budget
So what’s the takeaway for your Tuesday morning commute? Money is a game of inches, not dunks. The 60% bankruptcy rate isn’t a judgment on those players—it’s a reminder that sudden wealth is a skill, not a reward. You don’t need to be rich to be wise; you just need to be smart with what you’ve got.
Next time you see a highlight reel of a rookie buying his mom a house, smile. But then ask yourself: does that house come with a 30-year mortgage? Because at the end of the day, financial freedom isn’t about how much you earn; it’s about how much you keep. And that’s a stat that never lies.