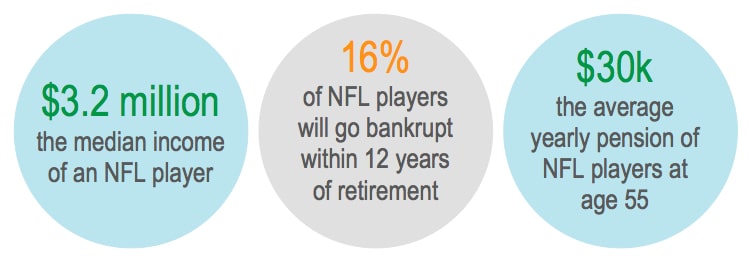
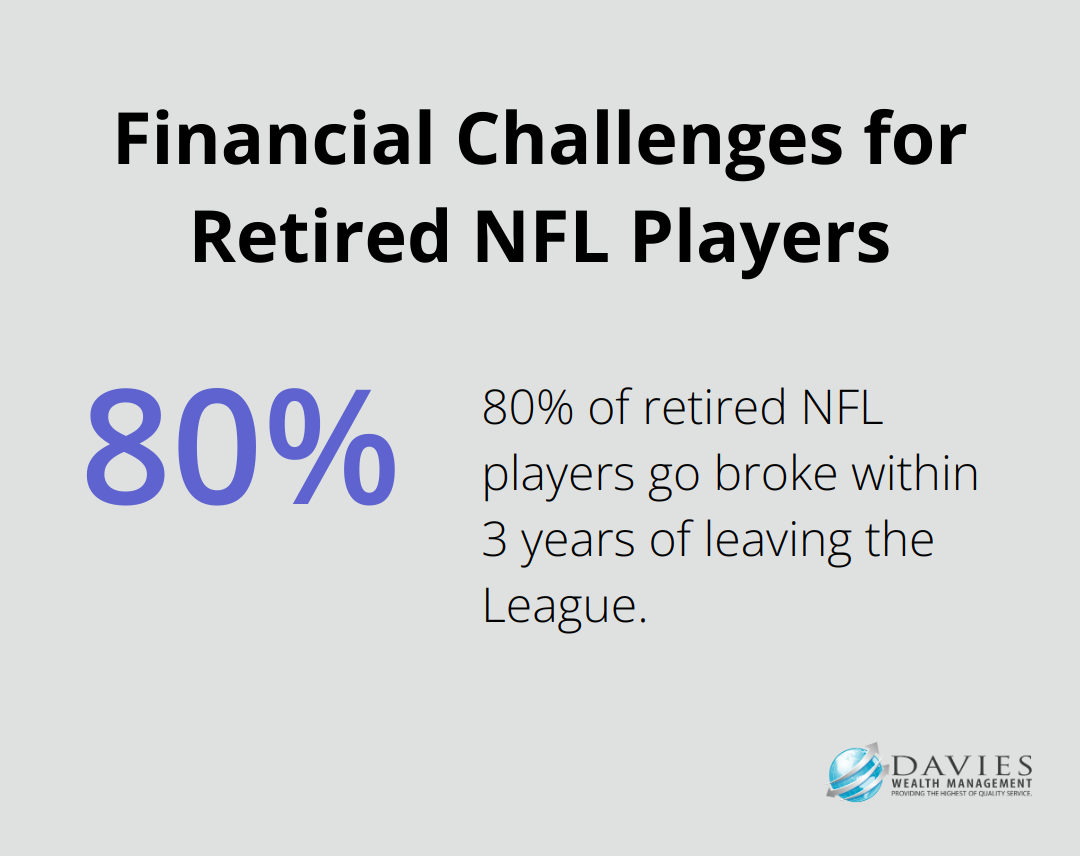
Let’s be real: when you picture an NFL player, you’re probably imagining a mansion, a fleet of cars, and a bank account that could fund a small country. The reality, though, is a lot less glamorous. Studies suggest that a staggering 78% of NFL players go bankrupt or face serious financial stress within just two years of retiring. That’s nearly eight out of ten guys who were once making millions, now struggling to pay the bills.
It sounds like a punchline, but it’s a sobering statistic that the league and players themselves are trying to change. You don’t have to be a pro athlete to learn from their mistakes. In fact, their financial pitfalls are surprisingly relatable to anyone who’s ever gotten a raise and suddenly felt invincible.
The Numbers Don’t Lie (And They’re Ugly)
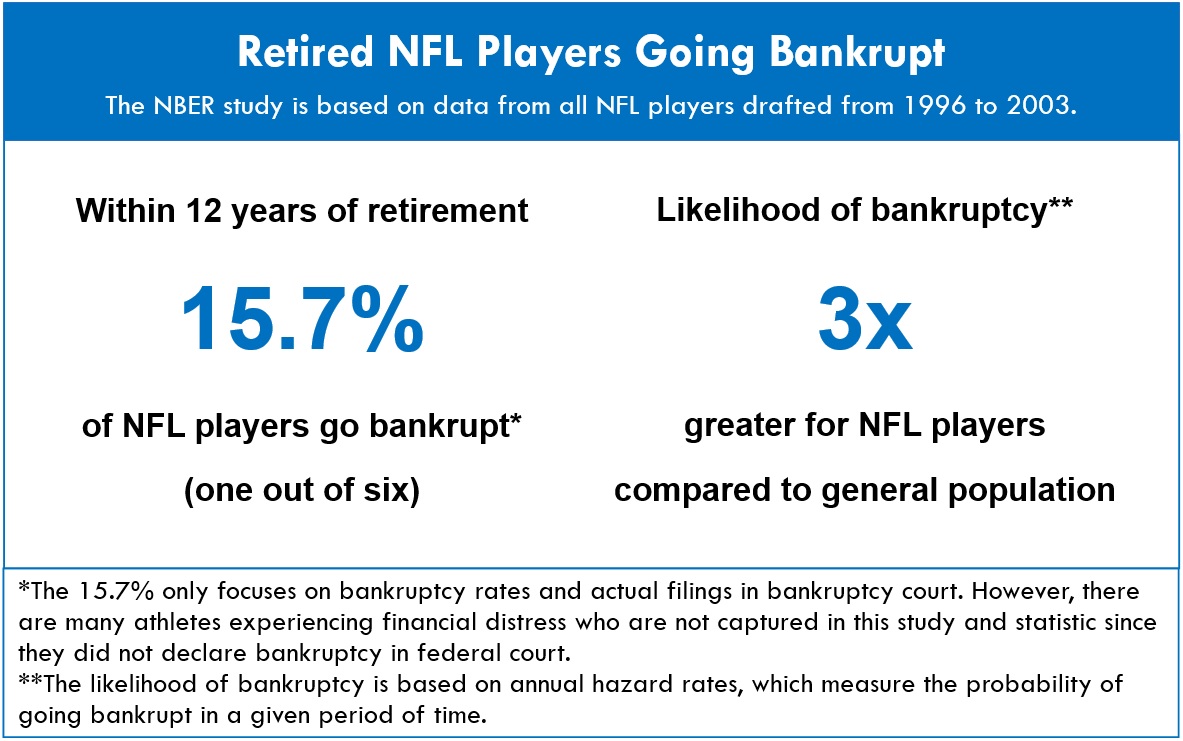
The most cited study, by Sports Illustrated in 2009, put the bankruptcy rate at 78% for NFL players within two years of retirement. More recent data from the NFL Players Association suggests the number may be closer to 16% for the first few years, but the long-term picture remains bleak. For context, NBA players aren’t far behind, with 60% going broke within five years of leaving the game.
Must Read
Why so many? It’s not just about buying flashy cars. The average NFL career is just 3.3 years, and the median salary is around $860,000—which sounds huge until you factor in taxes, agent fees, and the pressure to support an entire entourage. One bad injury can end a career and the paychecks instantly.
Even superstars aren’t immune. Legendary running back Adrian Peterson filed for bankruptcy in 2024, despite earning over $100 million in his career. And who can forget the cautionary tale of Mark Brunell, who lost $5 million in a single business deal? The pattern is a familiar one: fast money, faster spending, and zero financial literacy.
The Culture of “Keeping Up”
There’s a psychological trap at play called “lifestyle inflation.” When you’re in the locker room, the guy next to you might be driving a Lamborghini, so you feel pressured to get a Ferrari. This isn’t just an athlete problem—it’s a universal human flaw. Think about when you got your first real job and suddenly felt the urge to upgrade your phone, your wardrobe, and your coffee habit.
 Why Professional Athletes Need Specialized Financial Planning | Davies
The difference? An NFL rookie’s first check can be over $200,000 after taxes. For a 22-year-old, that’s like winning the lottery without any financial training. Friends and family often come out of the woodwork asking for loans, and the “yes” muscle is hard to build. The result is a perfect storm of debt, bad investments, and eroded savings.
On top of that, players face health care costs that few of us consider. Many retire with chronic pain, addiction issues, or cognitive problems from repeated concussions. Medical bills don’t stop just because the cheering does. That’s a sobering reminder that wealth without health is a fragile house of cards.
5 Lessons from the NFL (For Your Wallet)
1. Bet on the Emergency Fund, Not on Free Agency. Financial advisors recommend having 6-12 months of living expenses saved. For an NFL player, that might look like $50,000. For you, it’s a solid three months of rent and groceries. Don’t skip this.
 The NFL's Hidden Crisis: Why So Many Players Go Broke
2. Be a “Boring” Investor. Many athletes lose millions on fast-food franchises, car washes, or venture capital schemes they don’t understand. The smart ones, like Peyton Manning, stick with index funds and real estate they can actually manage. Low-risk, compound interest is the real MVP.
3. Cut the Entourage. The average NFL player supports 5-7 people on their payroll. That’s a lot of “managers,” “cousins,” and “best friends.” In real life, no one needs a personal hype man on salary. Keep your circle small and financially independent.
4. Learn to Say “No.” Saying no to a buddy’s business idea or a family member’s “once-in-a-lifetime” opportunity is hard. But financial freedom is built on boundaries. Practice a polite but firm, “I love you, but I can’t invest right now.”
 From Stoked to Broke: Why Are So Many Professional Athletes Going
5. Plan for the End at the Start. NFL careers end abruptly. So do jobs, relationships, and good health. Live below your means—even when you’re at your peak earning years. That’s the secret to never being broke, no matter your profession.
Cultural References That Hit Home
Remember the movie “The Blind Side”? Michael Oher’s story is inspiring, but his real-life financial battles later made headlines. Or think of Mike Tyson, who famously said, “If I’d had to work a regular job, I’d probably be a billionaire.” Instead, he went bankrupt. The lesson is timeless: money flows out as fast as it comes in if you don’t have a bucket.
Even pop culture gets it. In “Ballers” (the HBO show with Dwayne Johnson), every episode features a player blowing cash on cars, clubs, or shady deals. It’s fiction, but it’s drawn from real data. The show’s tagline could be, “Make millions, lose it all, repeat.”
 What Time Do Professional Athletes Go To Bed at Richard Groves blog
One fun fact: the NFL actually offers a Financial Literacy Program for rookies, but attendance is voluntary. Guess what? Most players skip it. Yikes. Compare that to the NBA, which mandates rookie financial training. The result? NBA players tend to have slightly better long-term savings habits.
The Reflection: What This Means for Your Morning Coffee
You don’t need a Super Bowl ring to learn from these statistics. The core problem isn’t the size of the paycheck—it’s the rate of spending relative to the rate of earning. Whether you make $50,000 or $5 million, the math is the same: if you spend more than you save, you’re one bad week away from broke.
So, the next time you’re tempted to buy that unnecessary gadget or order takeout for the fifth night in a row, whisper this to yourself: “Don’t be a 78% statistic.” Your financial future doesn’t require a Hail Mary pass—just a single, easy-going commitment to live a little smaller than you can afford. That’s the real win.
And hey, if you do hit the lotto or get that promotion, maybe hire a CPA before you buy the yacht. Use that financial literacy program. Your future self—and your bank account—will thank you.