Let’s be real: when you hear “Rich Dad Poor Dad,” you probably picture a guy in a Hawaiian shirt sipping a cocktail while his accountant does math. Robert Kiyosaki’s 1997 classic turned personal finance into pop culture. But here’s the twist—the book’s net worth isn’t just about cash in the bank. It’s a mindset, a lifestyle, and yes, a little bit of a hustle.
The Numbers Game (Sort Of)
Kiyosaki’s own net worth is a moving target. Estimates bounce from $80 million to over $100 million, but he’s famously cagey about exact figures. He’d tell you that tracking his net worth is like checking the weather—it changes daily. The real wealth, he argues, is in your financial education, not your portfolio balance.
Here’s a fun fact: Kiyosaki trademarked the phrase “Rich Dad” back in 1998. That intellectual property alone is worth millions. It’s like owning the word “avocado” during brunch season.
Must Read
What Rich Dad vs. Poor Dad Actually Means
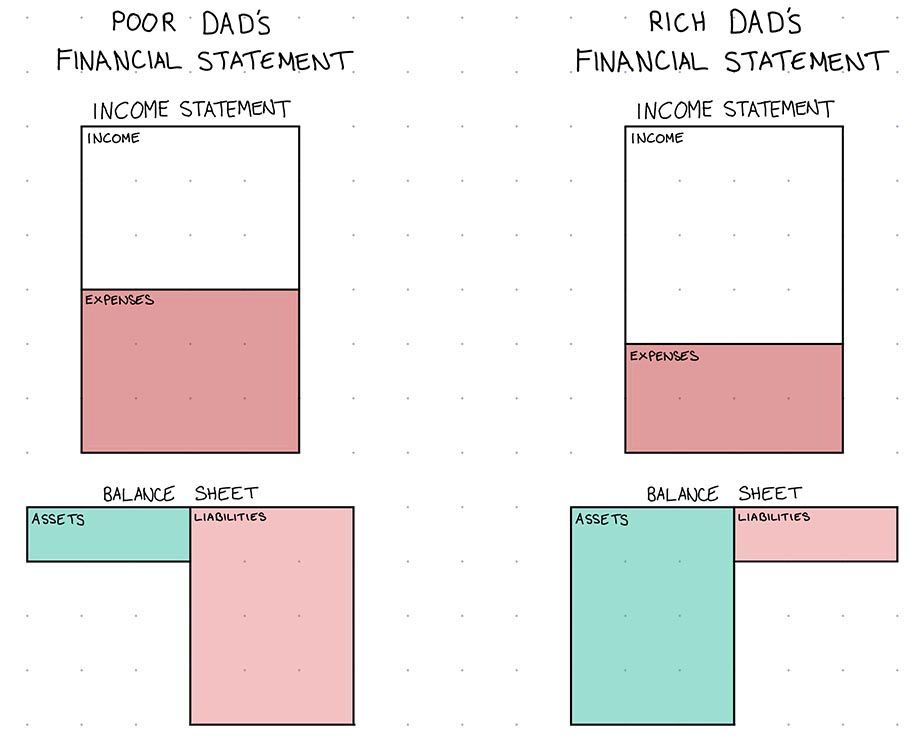
Poor Dad is the hardworking employee who saves, clips coupons, and prays for a pension. Rich Dad is the entrepreneur who buys assets that buy him more time. The book’s core lesson? Your house isn’t an asset—it’s a liability unless it pays you rent. Ouch. Sorry, HGTV.
Think of it like this: Poor Dad drives a reliable sedan. Rich Dad owns the car dealership. Same road, different view.
 Rich Dad, Poor Dad - Robert Kiyosaki - Zusammenfassung
Practical Tips to Boost Your Own Net Worth (Rich Dad Style)
Start with your paycheck. Kiyosaki says to pay yourself first—like, literally write a check to your investment account before you pay Netflix. Even 10% a month builds a snowball. Automate it so you won’t miss the coffee runs.
Buy assets, not liabilities. That new iPhone? Liability. A rental property that cash-flows $200 a month? Asset. The line is blurry, so ask: “Does this put money in my pocket or take it out?” If it’s the latter, you’re being a Poor Dad.
Learn one new thing about money every week. Read a book, listen to a podcast, stalk a finance influencer (the legit ones). Kiyosaki says school teaches you to be a worker, not a boss. Unlearn that.
 The Path to Financial Freedom: Insights from Robert Kiyosaki’s Rich Dad
Cultural References That Hit Different
Remember the scene in The Wolf of Wall Street where Jordan Belfort sells penny stocks? That’s the wrong kind of hustle. Rich Dad’s vibe is more Breaking Bad—use your skills to create a system that works while you sleep (minus the meth lab).
Or think of Taylor Swift. She owns her masters, her tour, and her brand. That’s Rich Dad energy in a glittery bodysuit. She’s not just a singer; she’s an asset machine.
 Rich Dad Poor Dad Book Summary in Hindi (रिच डैड गरीब डैड
The Haters and the Hype
Let’s be honest—critics say Kiyosaki oversimplifies. Real estate isn’t always passive, and not everyone can buy a duplex in Brooklyn. Fair point. But the spirit of the book is about mindset, not a step-by-step guide. You can apply it to a side hustle, a blog, or even flipping vintage clothes on Depop.
Fun fact: Kiyosaki filed for bankruptcy for one of his companies in 2012. Irony, right? But he bounced back. Because Rich Dad doesn’t fear failure—he rents it out and calls it a tax write-off.
Your Net Worth Is Not Your Worth
Here’s the part they don’t put on book jackets. Net worth is a number, not a soul. You can have millions and still feel broke inside—just ask any celebrity after a divorce. Kiyosaki’s real gift is getting you to think about money, not worship it.
 Rich dad poor dad summary – Artofit
So grab a latte (from your investment account’s passive income), and ask yourself: “Am I playing the Poor Dad game or the Rich Dad game today?” Usually, it’s a mix, and that’s okay.
Easy Morning Reflection
Tomorrow morning, before you check your bank balance, take a breath. Ask: “What’s one thing I can do today to buy myself more freedom tomorrow?” Maybe it’s negotiating a raise, listing an old couch on Facebook Marketplace, or reading one chapter of a finance book. Small moves, Rich Dad style.
Because at the end of the day, the richest people aren’t the ones with the biggest houses. They’re the ones who know that time is the only asset you can’t buy back. Now go drink your coffee, and remember: that mug is a liability—unless you fill it with tips from your new side gig.