
The Million-Dollar Toes
You’ve probably joked about it. Maybe after stubbing your little toe on the coffee table for the fifth time this week, you groaned, “I should insure these things.” Well, believe it or not, people actually do that. It’s not just for supermodels or NBA superstars.
Insuring a body part is a real thing, and it’s weirder and more relatable than you think. Let’s dive into the strange world of body part insurance without needing a calculator or a lawyer’s letter.
First, Let’s Get Real: Who Does This?
You might picture someone like a famous violinist insuring their fingers for a million bucks. Sure, that happens. Keith Richards has famously insured his hands, and David Beckham covered his legs for a cool $70 million. But you don’t need to be a celebrity to play this game.
Must Read
Think about a professional chef who relies on their sense of taste and smell. Or a voice actor who freaks out at the first tickle of a cold. For them, a lost body part isn’t just an inconvenience—it’s their entire income vanishing.
So, the first rule is simple: your body part must be essential to your job. You can’t just insure your left earlobe because you think it’s cute.
The “Oh, So That’s How It Works” Moment
Here’s where it gets funny. You don’t just call up your insurance agent and say, “Hey, I want a policy on my tongue.” Instead, it’s usually a special “key person” or “disability” policy with a twist. The policy actually pays out if the part is lost or damaged in a way that stops you from working.
 Body Parts Insurance: A Complete Guide to Insuring What Matters Most
Imagine you’re a pianist. If you break a finger, the policy doesn’t buy you a new finger. It gives you a lump sum of cash to replace the income you’ll lose during recovery. It’s like a financial safety net for your weirdest, most specific talent.
And no, the insurance company doesn’t send a spy to watch you bite your nails. They just ask for a medical exam and a lot of paperwork.
The Hilarious Part: What Isn’t Covered?
This is where you’ll nod and laugh, because life is messy. Most policies have a huge list of exclusions. You know, the “don’t be an idiot” clause. For example, if you insure your tongue and then try to open a beer bottle with your teeth, they’re not paying out.
Same goes for extreme sports. Think you can insure your legs for skiing? Not if you’re doing it off a cliff. Some policies even exclude “pre-existing conditions” like a weak ankle you twisted in high school.
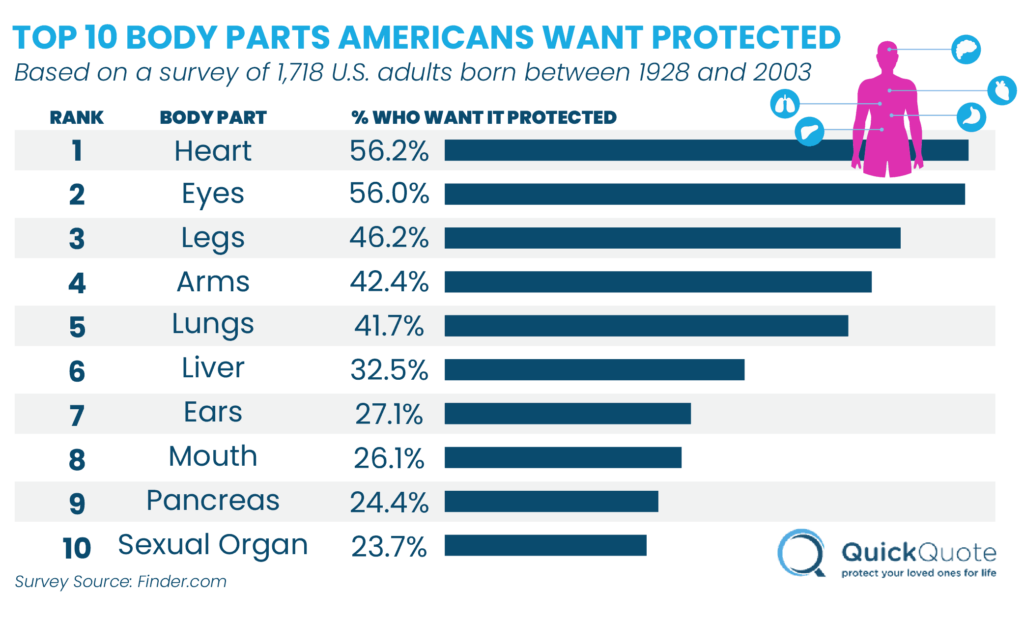 Insurance Companies That Insure Body Parts at Harry Roloff blog
One famous story? A model once tried to insure her smile, but the company denied her because she chewed gum. Gum! They said it increased the risk of jaw injury. Talk about a buzzkill.
How Do You Actually Get a Quote?
It’s surprisingly simple. You find a specialty insurer that deals with “celebrity” or “entertainment” coverage. Then, you sit down with an agent who will look at you with a straight face and ask, “How much is your left hand worth?”
You need to prove the financial value of that part. Do you have contracts that depend on your voice? Show the money. Do you have a signature dish that relies on your sense of smell? Get a letter from your boss. It’s basically a business deal for your biology.
The premium (what you pay) is usually a percent of the payout. So, if you insure your fingers for $1 million, you might pay $10,000 to $30,000 a year. That’s a lot of money, but not as much as losing your career.
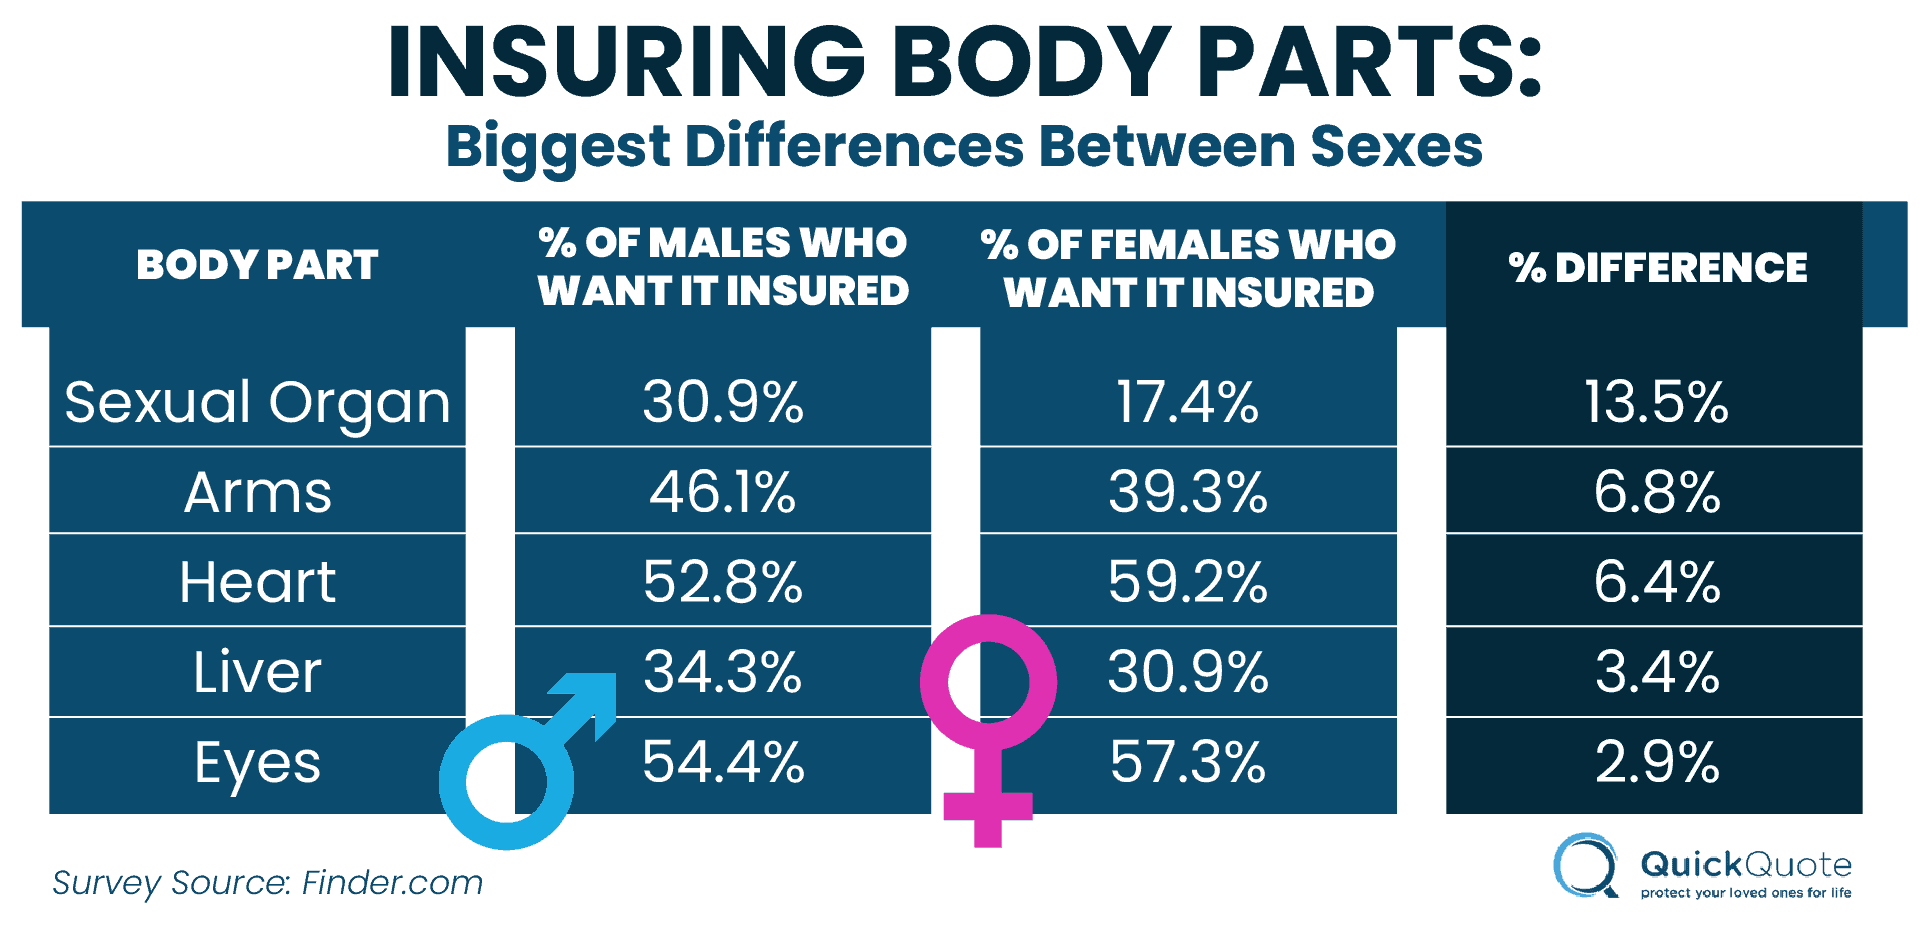 10 Common Body Parts You Can Insure [2026] | QuickQuote.com
The Everyday Person’s Version
Now, let’s bring this back to your living room. Most of us can’t afford a million-dollar pinky. But the habit of protecting your tools is something we all do. Think about it: you probably have a friend who wears gloves for every dishwashing task because they’re an artist. That’s their version of body insurance.
Or, consider the person who buys “accident insurance” through their job. That’s basically a low-rent version of body part insurance. You break a toe and get a check for $500. It’s not glamorous, but it beats crying over a broken bone.
In a way, we all insure our parts every day. You wear a seatbelt (insurance for your neck). You don’t stick a fork in a toaster (insurance for your fingers). It’s just that some people formalize it with paperwork and a bank account.
The Awkward Truth: It’s Weird to Talk About
The real reason this topic makes you smile is because it’s deeply awkward. Have you ever had to explain to your spouse that you just spent $2,000 to insure your singing voice? They might look at you like you’ve lost your mind.
 Body Parts Insurance: A Complete Guide to Insuring What Matters Most
But here’s the kicker: nobody laughs when the claim comes through. When a chef loses their sense of taste to COVID, or a guitarist has a car accident, that policy suddenly feels like a genius move. It’s the same for any passion project you have.
So, next time you stub your toe, don’t just curse. Give it a little nod. That wiggly, painful little digit is probably worth more than you think. And if you’re a professional toe-stubber? Well, you know who to call.
The Final Verdict
Insuring a body part is equal parts ridiculous and practical. It’s a reminder that your body is your first business tool, even if your business is just “being you.” You don’t need a Hollywood contract to appreciate that your voice, your hands, or even your weirdly flexible thumbs are assets.
So go ahead. Give your hands a little rub. Thank your knees. And if you ever become famous for something, maybe call an agent. Until then, just avoid the coffee table. That’s the cheapest insurance of all.